A monthly, data-led briefing for CEOs and commercial and bid leads at renewable developers and IPPs. It covers onshore wind, solar, BESS and offshore wind, mainly in GB, with France, Ireland and Iberia where they matter. Every figure is taken from a public source, which is numbered and listed at the end with its URL and date. Anything that is our own estimate or judgement is marked ASSUMPTION. Data were checked on 16–18 October 2026.
This month
Three things a CEO should act on this month
1. Get your AR8 strike-price floor and your CfD-or-PPA call signed off before 19 November.
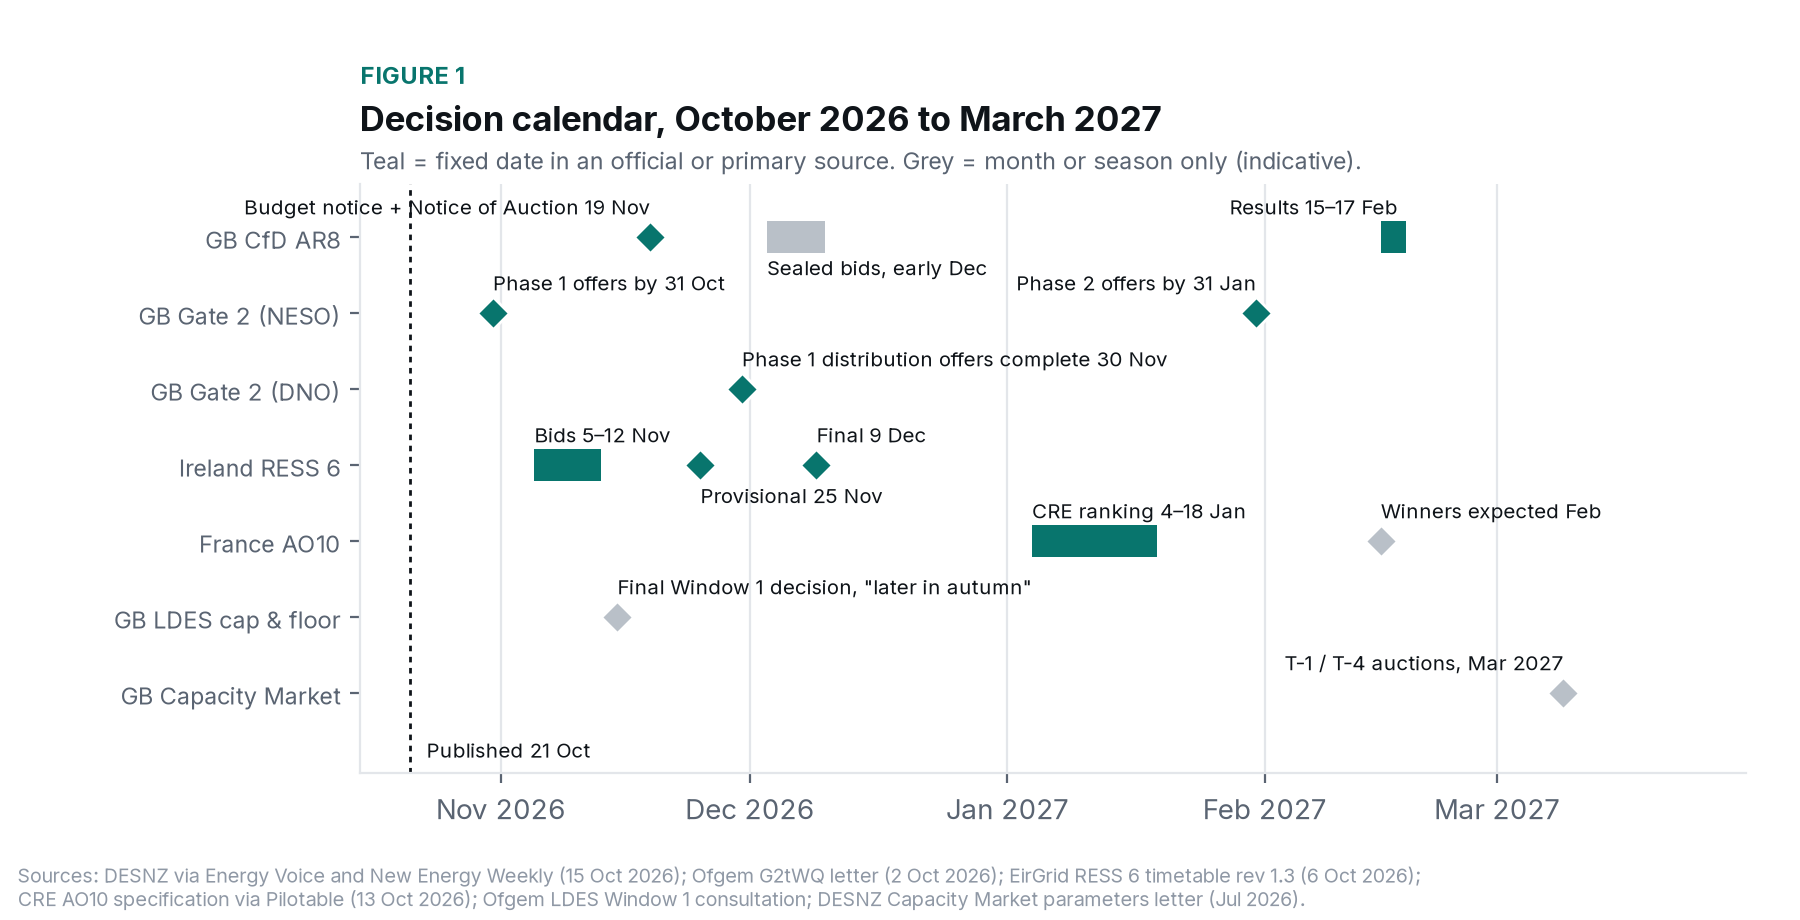
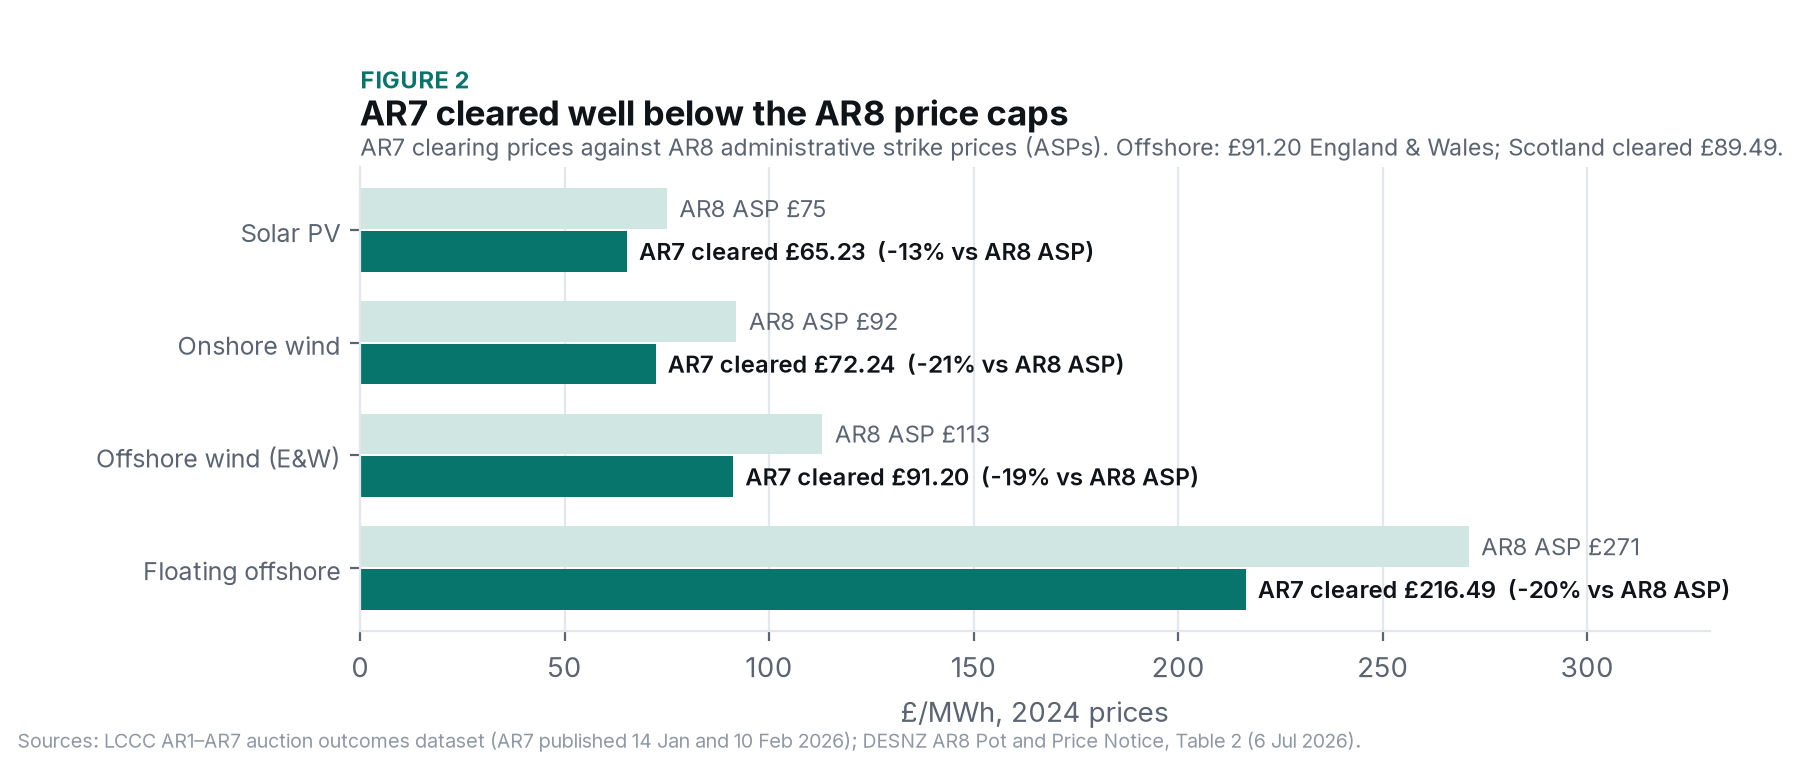
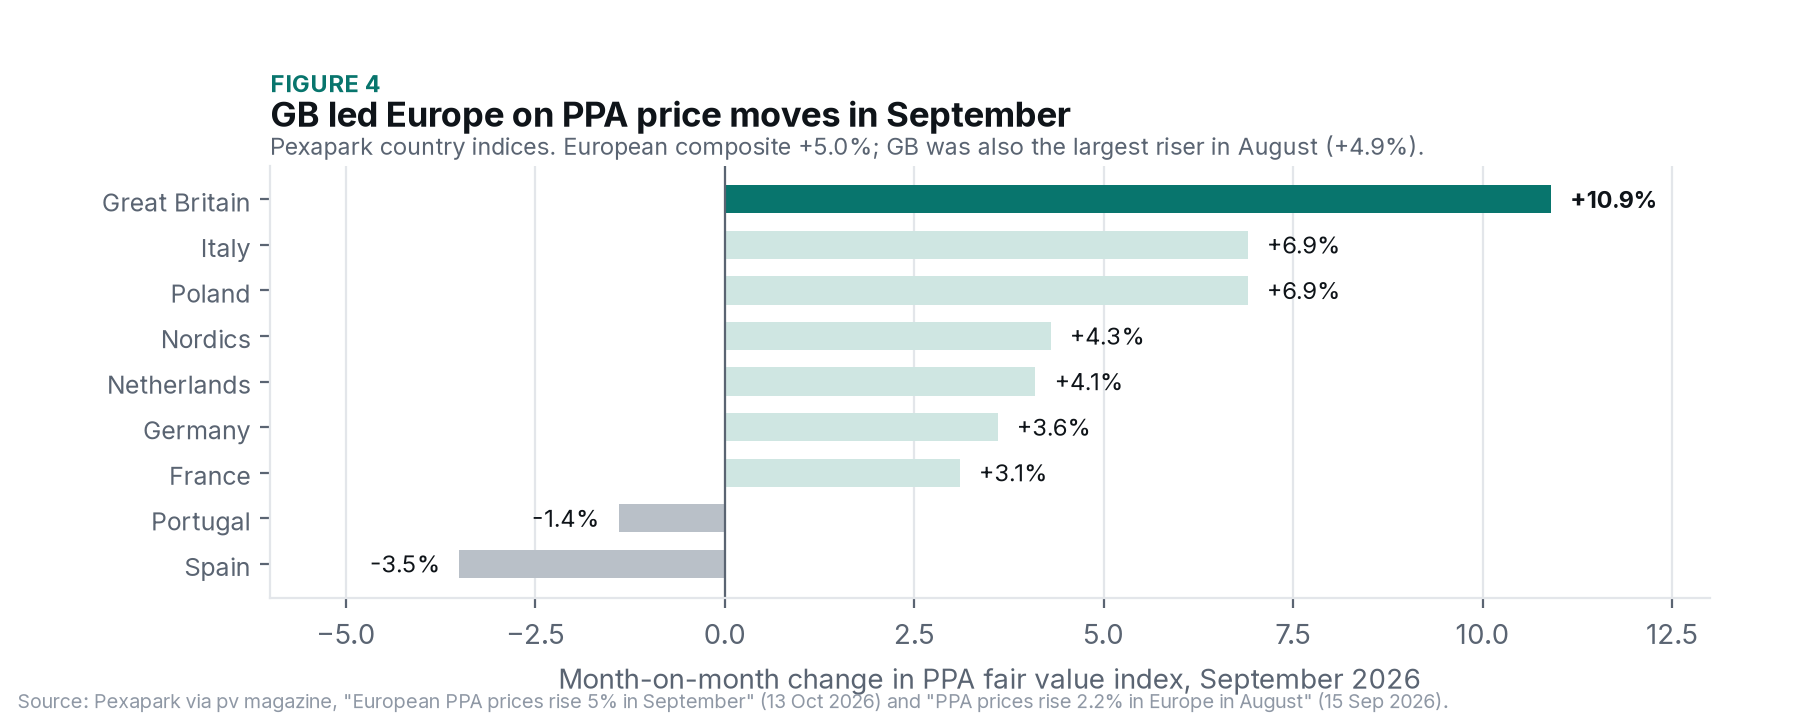
DESNZ publishes the AR8 Contract Budget Notice and NESO the Notice of Auction on 19 November 2026. Sealed bids follow in early December, and results are expected 15–17 February 202712. In AR7 every main pot cleared 13–21% below the AR8 price caps (ASPs): solar at £65.23 against £75, onshore wind at £72.24 against £92 (2024 prices) 35. Government will have sight of bids in Pots 1–4 3. Meanwhile GB short-term power has averaged £145/MWh so far in October, double October 2025 27, and Pexapark's GB PPA index rose 10.9% in September 28. ASSUMPTION: higher forward prices make the PPA or merchant route more competitive with a CfD, so the comparison has to be re-run on current curves. Leaving it until budget day would be a mistake.
Act: get investment committee approval for a walk-away price and up to four flexible-bid variants by mid-November 4.
2. Treat every Gate 2 offer as a board decision with a deadline.
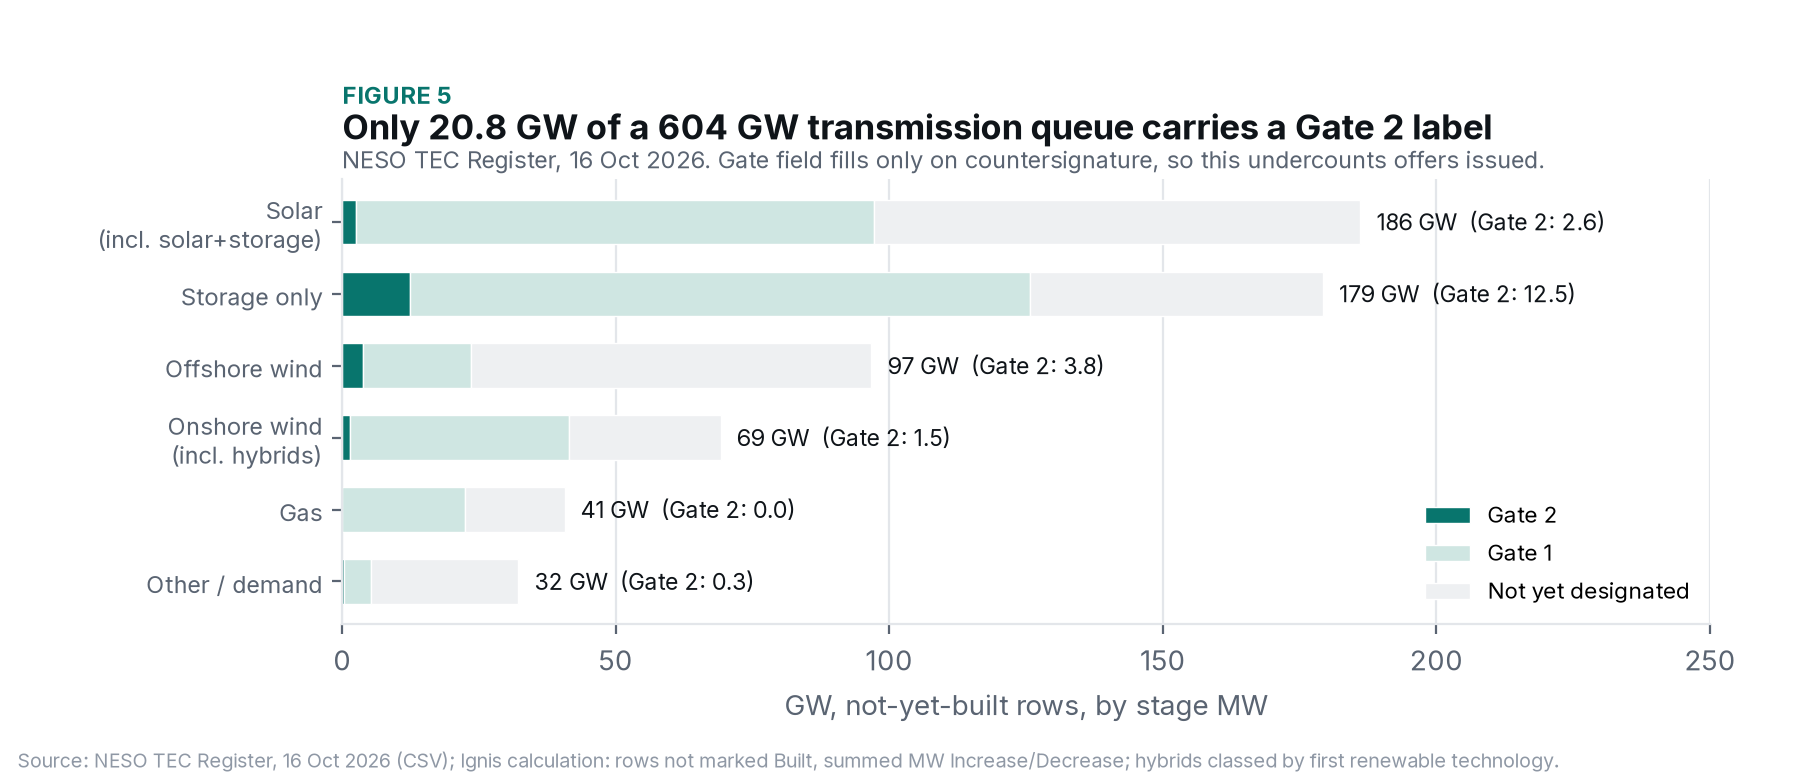
NESO must issue the remaining Gate 2 Phase 1 offers (about 62) by 31 October 2026 after a second extension. Phase 2 follows by 31 January 2027 6. Acceptance windows are already closing. On National Grid Electricity Distribution's published schedule, the next batches close on 26 Oct, 2 Nov, 9 Nov, 16 Nov and 23 Nov (Batch 4 closed on 19 Oct) 8. Only 20.8 GW of the 604 GW not-yet-built transmission queue has a countersigned Gate 2 label so far (Figure 5) 10.
Act: review each offer's date, securities and works against its route to market (CfD round, Capacity Market, cap and floor, PPA), then decide whether to accept, challenge or drop it before its window closes.
3. Have your contracted-revenue structure ready before you go to capital.
October's GB flexibility deals were built on contracted or optimised revenue. CIP took FID on the 350 MW / 1.4 GWh Kilmarnock South battery, which has a long-term Shell optimisation agreement 41. Econergy's Dalmarnock battery has a 10-year EDF floor and Santander debt 43. Ares bought into Statera's 1.9 GW portfolio 39. Across Europe in September, 16 flexibility agreements covered about 2.1 GW, including 925 MW of tolls 28. ASSUMPTION: lenders and equity are pricing BESS on the quality of its floor or toll as much as on the project itself.
Act: run a toll and floor process in parallel with financing, not after it.
1 · Auctions
1. Auction and tender calendar and results
Round
Status at 18 Oct 2026
Next milestone
Source
GB CfD AR8
On the longest indicative timetable because qualification appeals run first; the pending-applications route is not being used
Budget notice and Notice of Auction 19 Nov 2026; sealed bids early Dec; results 15–17 Feb 2027
Offshore wind 8,245 MW at £91.20 (England and Wales) and £89.49 (Scotland); floating 192.5 MW at £216.49 (published 14 Jan 2026). Solar 4,905 MW at £65.23; onshore wind 1,306 MW at £72.24; tidal 20.9 MW at £265 (10 Feb 2026). All in 2024 prices
A capacity market was created by Orden TED/966/2026 (15 Sep 2026); new investment is limited to renewables, storage and demand. The first offshore wind tender has no date
The AR8 administrative strike prices, in 2024 prices, are solar £75, onshore wind £92, offshore wind £113, floating offshore £271 and tidal stream £371/MWh 3. AR7 cleared 13% (solar), 21% (onshore), 19% (offshore, England and Wales) and 20% (floating) below those caps (Ignis calculation from 35). AR8 adds government visibility of floating and deepwater offshore bids, so bid visibility now covers Pots 1–4 3.
Wholesale (GB).
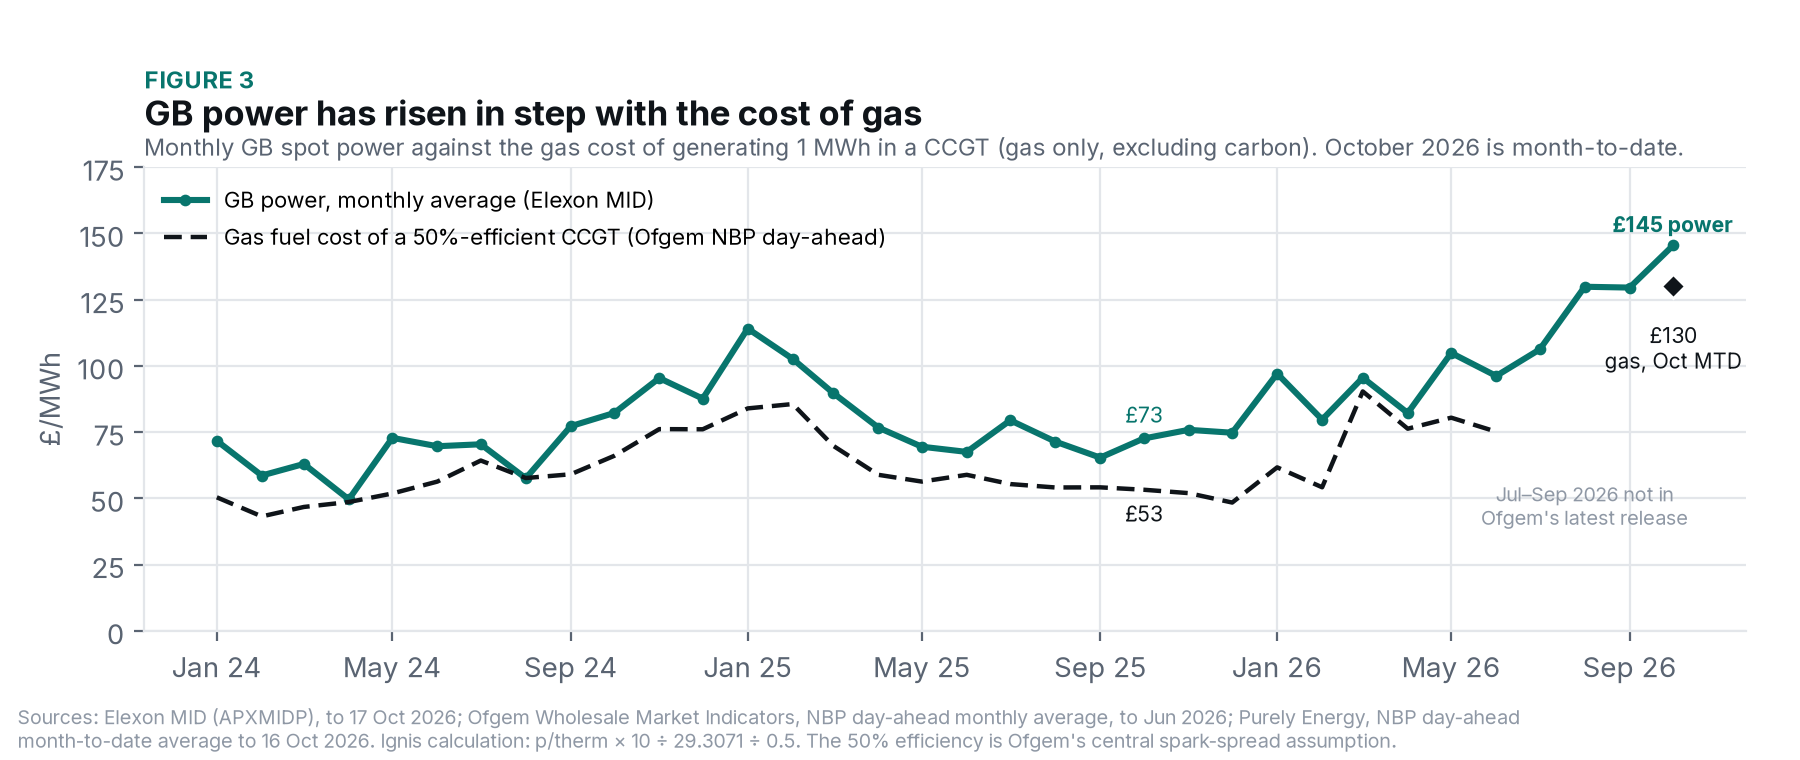
Elexon's Market Index Data (APX), averaged by month, was £145.49/MWh for 1–17 October 2026, against £129.56 in September 2026 and £72.59 in October 2025 27 (Ignis calculation). No half-hour has priced below zero so far this October, against 29 in October 2025 27. These are short-term spot prices, not forwards.
What is driving GB power prices up
Gas sets the price, and gas has nearly tripled. Gas-fired plant still sets the marginal GB power price for much of the time 5152. NBP gas was about 217p/therm on 18 October, up 168% on a year earlier49. Nov-26 closed at 216.83p on 13 October, up 15% in a week on colder forecasts 50. At Ofgem's 50% CCGT efficiency 59, October's gas cost per MWh is about £130, against £53 a year ago: roughly the whole +£73 rise in spot power (Figure 3; Ignis calculation from 275859).
The trigger is the Iran conflict and the Strait of Hormuz.
Day-ahead NBP jumped from £26.7 to £47.0/MWh on 1–3 March as the conflict escalated 51.
In Q2, the US–Israel–Iran conflict and Hormuz disruption drew LNG cargoes away from the UK 52.
In July, US–Iran exchanges lifted day-ahead NBP 34% in a month 53. Reuters (19 August) reported the "Iran war" pushing the October price cap to a three-year high 5455.
Stalled peace talks kept prices rising in September 56. In the week to 13 October, shipping attacks, Norwegian outages and Asian LNG at $29.61/MMBtu added more 50.
Low storage amplifies the shock. At the end of July, EU storage was 57.7% full and UK storage 27% 53. By 12 October Europe was about 73.75% full, over nine points below last year 50. With little storage of its own, the UK tracks the continental fill 58.
Wind and weather drive the swings. Day-ahead power rose from £130 to £160/MWh over September, largely on a sharp fall in wind into October 56. Strong wind took next-day power to £33.89 on 9 October 50. Demand spikes came from a January cold spell 51 and summer heatwaves that raised gas burn for power 5255; forecasts now show temperatures up to 3.8°C below normal 50.
Carbon is minor. UK ETS allowances were £58.26/t at the end of July 53 and £65.92/t on 13 October, on UK–EU linking reports 50. The 2026 reference price is £49.41/t 57. ASSUMPTION: at about 0.37 tCO₂ per MWh for a CCGT, that adds roughly £3–6/MWh against about £77 from gas.
Nuclear and interconnectors: not established. Q2 nuclear output fell 12% year on year and NESO capped some interconnector trades from May 52, but no public source ties October's rise to an outage.
Forwards price the premium into 2027, not beyond. On 16 October, Summer-27 power settled at £127.36/MWh and NBP Summer-27 at 164.30p/therm. Summer-28 power was £80.69 and Summer-29 £72.80 58. Summer-27 power was £83.00 at the end of July 53 and £104.75 at the end of September 56. Caveat: most figures here are from broker and consultancy notes, not exchange data.
What it means for developers.ASSUMPTION: this is our judgement, not a forecast.
CfD against PPA or merchant. The premium sits in the next 12–18 months. By Summer-28 and Summer-29 the curve (£73–81, nominal) is back below the onshore wind ASP of £92 and near AR7's £72.24 (both in 2024 prices) 3558. Projects that can generate before 2028 can capture today's prices through a short PPA or merchant phase. AR8 projects delivering later mostly cannot, so the CfD stays the bankable floor.
BESS. Imbalance prices ran from −£13.30 to £254/MWh within three days in October 50. Gas-set peaks and wind-set troughs widen spreads, which supports merchant revenue. Tolls and floors signed now may be priced off this unusual volatility, so test them against a calmer 2028 curve.
Cost of delay. A 50 MW onshore wind farm at a 30% load factor produces about 11 GWh a month. Each month late forgoes about £1.4m at the Summer-27 forward, but only about £0.8m at Summer-29. Delay is most expensive now.
PPAs.
Pexapark's GB PPA index rose 10.9% month on month in September, the largest rise in Europe (European composite +5%). Spain (−3.5%) and Portugal (−1.4%) fell 28.
In August, GB rose 4.9% after Pexapark revised its market-price-risk assessment: about +£5/MWh for a 10-year PPA at comparable start dates 29.
LevelTen's Europe-wide solar P25 rose 2.8% in Q2 2026, ending four quarters of decline; wind fell 1.6% 31.
LevelTen's latest public UK figure is a solar P25 of €87.36/MWh for Q4 2025 30. Its Q3 2026 European index is due on 22 October32.
ASSUMPTION: a CfD bid floor modelled against last spring's curves is now out of date.
3 · Grid
3. Grid: connections reform and the queue
This month.
On 2 October, Ofgem agreed NESO's second extension for Gate 2 Phase 1 offers to 31 October 2026. It affects about 62 offers, delayed mainly by NGET transmission owner construction offers (TOCOs), plus about 25 delayed at customer request 6.
Phase 2 offers are due by 31 January 2027. Distribution offers should be complete by 30 November 2026 (Phase 1) and 31 March 2027 (Phase 2) 6.
By 10 June, NESO and the DNOs had issued updated offers to 713 projects, about 37 GW 9. NESO releases offers location by location 7.
National Grid Electricity Distribution has split its Batch 10. Batches 10 and 11 now expect offers on 20 and 27 November, with acceptance by 28 December and 4 January 8.
Register level: 690.0 GW (MW connected plus MW increase/decrease, all rows).
Not-yet-built queue: 604 GW. Of this, Gate 1 is 295.0 GW, Gate 2 is 20.8 GW (124 projects) and 288.3 GW is not yet designated.
By technology: storage-only projects are 179 GW and solar, including solar plus storage, is 186 GW.
Change: a public tracker using the same basis puts the register at 684.3 GW on 25 Aug and 691.3 GW on 13 Oct. Most of the rise came from 29 projects (11.1 GW, mostly storage) joining on 13 Oct, 25 of them already holding a Gate 1 label 11.
Connection years: queue capacity peaks at 83.1 GW in 2033 and 95.1 GW in 2037, by the year in MW Effective From 10.
Caveat: the Gate field fills only when an agreement is countersigned, so it undercounts offers issued 11.
4 · Consents
4. Consents
Date (2026)
Project
Decision
Source
8 Oct
Green Hill Solar Farm (Northamptonshire and Milton Keynes), up to 500 MW solar with storage
ASSUMPTION: large solar DCOs are being granted. The risk now sits in local opposition and decision-deadline slippage (Botley West has been extended once), not in outright refusal. We found no October refusal of a GB energy DCO. For context, the Morgan and Morecambe offshore transmission assets DCO was granted on 14 September 35. Not covered: we did not systematically review October decisions under the Town and Country Planning Act (TCPA) or Scottish Section 36 (S36).
5 · Capital
5. Deals and capital (October 2026)
Date
Deal
Detail
Source
2 Oct
CIP: FID on Kilmarnock South BESS (South Ayrshire)
350 MW / 1,400 MWh; more than €270m committed; COD Q1 2028; long-term Shell optimisation agreement
Ares takes a minority stake in Statera's 1.9 GW portfolio
Includes Carrington Storage (680 MW) and Thurrock Flexible Generation (750 MW); Ares Infrastructure Equity's first European investment; terms not disclosed
Late September, for context: Revera reached financial close on the 400 MW / 800 MWh Hunterston BESS with a BP toll and a Danske Commodities floor (25 Sep) 46.
30 Nov: Gate 2 Phase 1 distribution offers complete 6.
Ofgem LDES Window 1 final decision, expected "later in autumn" 24.
Pexapark's October PPA index, due mid-November (ASSUMPTION based on its usual monthly cadence).
The question for November: does the AR8 budget, read against £130–145 spot prices, make PPA or merchant the better route for marginal solar and onshore wind? We will run that comparison when the budget is published.
Method
Method and data notes
Wholesale: simple average of half-hourly APXMIDP prices with non-zero volume, from Elexon's API, 1 Jan 2024 to 17 Oct 2026. October 2026 is month-to-date. Full series in data/.
TEC Register: rows not marked Built, summed "MW Increase / Decrease". Hybrid sites are classed by their first renewable technology. Third-party trackers using other conventions report different Gate 2 totals, for example 15.4 GW countersigned on 16 Oct 48 and 19.2 GW on 13 Oct 11.
Gas cost of power (Figure 3): NBP p/therm × 10 ÷ 29.3071 = £/MWh of gas; ÷ 0.5 for a 50%-efficient CCGT (Ofgem's central spark-spread assumption). Gas only, excluding carbon. October 2026 uses Purely Energy's day-ahead month-to-date average to 16 Oct; Ofgem's monthly series ends in June 2026. Carbon effect: ASSUMPTION of about 0.37 tCO₂/MWh for a CCGT, applied to the UK ETS rise above the 2026 reference price.
UK gas storage: mid-October public figures disagree (about 62% per Catalyst on 13 Oct 50; 42.4% per Purely Energy on 15 Oct 58), so we quote only the end-July figure.
CfD prices: AR7 and AR8 are in 2024 prices. Earlier rounds are in 2012 prices and are not comparable.
Not verified:
Exact AR8 sealed-bid window dates (secondary reports say early December; NESO confirms them on 19 Nov).
The Gate 2 Phase 1 capacity still to be issued.
GB-specific LevelTen P25 levels for Q1–Q3 2026.
Spain's offshore auction date.
Any October refusal of a GB onshore project under TCPA or S36.
Any specific nuclear or interconnector outage behind October's price rise.
The Reuters article 54 is paywalled; its 'Iran war' wording is confirmed via its syndicated text and Cornwall Insight's own release 55.
13Windtech International, "France's AO10 offshore wind tender closes for bids", 14 Oct 2026. www.windtech-international.com
14Pilotable.fr, "Veille énergie — 13 octobre 2026". pilotable.fr
15Sud Ouest, AO10 and Oléron (accessed 17 Oct 2026). www.sudouest.fr
16L'Echo du Solaire, "Appel d'offres solaire au sol : le prix moyen chute de 23%, à 61,33 €/MWh", 12 Oct 2026 (CRE deliberation published 9 Oct). www.lechodusolaire.fr
53Optimised, "Monthly energy market insight: August 2026" (July 2026 data), 2026. www.optimised.net
54Reuters, "Britain's energy price cap to hit three-year high in October, Cornwall Insight says", 19 Aug 2026. www.reuters.com
55Cornwall Insight, "Energy bills forecast to hit three-year high", 19 Aug 2026. www.cornwall-insight.com
56NRLA (Clear Utility Solutions), "Business energy market update: October 2026", 7 Oct 2026. www.nrla.org.uk
57GOV.UK, UK ETS Authority, "UK ETS: carbon price for use in civil penalties, 2026", 28 Nov 2025. www.gov.uk
58Purely Energy, "Today's UK wholesale prices" (settlements to 16 Oct 2026), accessed 18 Oct 2026. www.purelyenergy.co.uk
59Ofgem, Wholesale market indicators: NBP day-ahead monthly average (to Jun 2026) and spark spread methodology, accessed 18 Oct 2026. www.ofgem.gov.uk
Ignis Leadership provides commercial AI for energy projects, from last-mile development to financial close. ignisleadership.com. This monitor is for information only and is not investment advice.